

WTI (Dec)* $97.82 -82c, Brent (Dec) $108.79 -76c, Diff -$10.97 +$5.08.
USNG (Nov) $2.96 -10c, UKNG (Nov) 218.42p -1.69p, TTF (Nov) €88.665 -€0.49.
*Denotes WTI November contract expiry.
Due to circumstances outside my control, the blog did not go last night, I’m told that this was a global problem and this is what I was told. The issue is an ongoing infrastructure disruption affecting systems and services in the Google UK-based data center.
I have updated the blog with todays prices and news, the oil price comment is in two sections…
Oil price
Yesterday oil fell a little ahead of the WTI expiry and as rumours swept the market that the Iran President was in meetings with the Pakistan peace envoys, ie the army…And the Houthis continued with the military pressure on Saudi Arabia which kept exports down but further support but supporters of the Saudis now include the UK who have pledged air support against missile attacks.
Some data yesterday, the API stats indicated the tight market, crude drew by 4.93m barrels against the whisper of -1.3m whilst gasoline drew by 2m b’s and unsurprisingly, distillates fell by 2.6m b’s. Stocks at Cushing actually built by 900/- barrels and the SPR drew by 300/-.
And US retail gasoline prices fell a little last week, a gallon of Exxon’s finest will still cost you $4.284 but if you use diesel it rose by 9.7 cents to $6.276 a gallon which is up by $2.656 year on year.
Today oil is up a little, December WTI has settled down to $98.41 up 59c whilst Brent is still up there at $109.23 up 44 cents this morning.
From yesterday, for what it’s worth…
Oil is up today WTI by a couple of bucks, Brent by just the one but over $110 which tells you something. But yesterday the differential narrowed significantly, back down to below $6 but maybe a touch technical as traders were covering short WTI positions ahead of the November contract expiry tonight. Meanwhile Brent was affected somewhat by the market’s vision of extra Russian crude potentially coming on the market.
But shortages continued as the dated market tells you as the Houthis attacked Saudi targets again including the Yanbu and Shaybah facilities and overnight against the King Khalid airport again. Other friends in the region have offered support, the latest being Egypt but so far nothing from the USA who are preferring to cosy up to Putin.
And on that note I repeat my previous mantras, neither the crude market nor the diesel market will be significantly changed by the rather pathetic US attempts to rig the domestic product market whilst all the time losing credibility. Indeed the IEA agrees, on CNBC a spokesman said that the extra product ‘won’t even touch the sides’.
On a domestic note it is interesting that the Ithaca boss told the FT that he will ‘redirect future spending’ if the UK Government doesn’t approve Rosebank. Finally, thanks to KeyFacts Energy there has been a significant shift in stance from the SNP, I quote here.
‘The Scottish National Party (SNP) has signalled a significant change in its approach to domestic oil and gas production, with party members voting at the SNP conference in Aberdeen to abandon the longstanding presumption against new oil and gas developments.
The decision marks a shift in the party’s approach to the future of Scotland’s North Sea industry, placing greater emphasis on domestic production, energy security, employment and the economic contribution of the offshore sector’.
Jackdaw gas field
The UK Government has rather belatedly approved the Jackdaw gas field in the UKCS and whilst it’s a shame that internal politics in the Labour party should hinder such a development, the fact that the owners have continued to invest means that it should be onstream within a month supplying c. 6% of the country’s gas needs.
The reason for the backtracking is given as ‘energy security’ and that the Chancellor is setting up an “Energy Wealth Fund’ and will use the proceeds to maintain their commitment to net zero. They haven’t mentioned of course that they need the tax revenue, that it will save high quality jobs mainly in Scotland and of course be net zero net positive as we will import less LNG from the USA and Qatar…
Whither Rosebank and others? I think that Rosebank will get the nod now that the Government has crossed the rubicon as it were. I do think that this first approval will be a good read across for investment in other, similar, developments, after all the OEUK has identified over £50bn of investment in other opportunities on the UKCS.
Into such categories I would place those opportunities that could be unlocked with the right regulatory and fiscal policies in place, into such categories I would place the redevelopment of the Greater Buchan Area which is not new and the partnership is putting it back into production.
We’re committed to moving towards renewable energy and reaching net zero by 2050. But even on our ambitious climate path, we’ll still require oil and gas as part of our energy needs for decades to come. That’s why we’re taking a pragmatic approach to the North Sea. We’re also establishing a new Energy Wealth Fund to invest in renewable energy, support the green transition and help reduce energy bills over the long-term.
Our approach will ensure we can boost our energy security, back British workers, ringfence future North Sea proceeds to speed up the green transition, hit our ambitious climate targets and – crucially – bring down bills.
Gulf Keystone Petroleum
GKP has announced a merger with ShaMaran and an operational and corporate update. The latter contains nothing new from the recent update and the combined company is looking in very good nick. With scale and lots of upside the assets offer significant growth potential.
So, this is a 50/50 ‘merger’ with the ShaMaran shareholders getting an 11% premium for their shares, but for their troubles GKP holders will get a $50 dividend sweetener with another $50 next year. It is worth noting that today Jon Harris, CEO has bought 14/- shares and Gabriel Papineau, CFO has bought 10/- shares in the company.
So, the combination will deliver a large high quality portfolio with the excellent Shaikan and Hamrin fields with cash flow also coming from the Atrush and Sarsang fields and making a strong Kurdistan and Iraq based company in the world’s top ten listed independents. The company will have strong production, some 53/- b/d and 2P reserves of 323m barrels is highly attractive and a force on the international stage.
But 50/50, I’m not sure, given that GKP has the excellent Shaikan field and is debt free I’m unconvinced that they deserve only 50% of the combined vehicle, a dividend of $50m now and another $50 promised to ‘facilitate’ the deal as it were.
Finally, I’m not convinced that the company should be selling out like this, but also to de-listing from the London market particularly as it isn’t necessary. I think that the retail shareholders have been hung out to dry in terms of timing, process and logic and they have been sacrificed on the altar of an Oslo main market listing.
The board may have the GKP CEO on it but the CFO moves off the board and of course William Lundin takes the Chair, the largest shareholder of ShaMaran is supportive as is the GKP biggest holder…
The explanation in the call was that to remain in London as a dual listing, which would be eminently sensible in my view, would involve higher costs and that liquidity in Oslo would be increased. Just without the retail shareholders who have stayed with GKP through thick and thin, and there was a lot of thin if you remember.
Given that I think that my views may be wide of the mark I asked the company for their views and in the interests of balance here is their reply.
- As we are a Bermuda incorporated company, there is no withholding tax regardless of the listing venue
We believe that a single liquid listing on the Oslo Bors main market is ultimately the best option for investors that will unlock better liquidity, pricing and valuation for the combined company. The Oslo Stock Exchange is a leading hub for international energy capital markets and investors active in the equity and debt markets in Oslo have an excellent understanding of Kurdistan and our companies, and a strong track record of support.
So, you pays your money and you take your choice…
Gulf Keystone and ShaMaran Petroleum Ltd. announce that they have signed a Bermuda merger agreement and a combination agreement to combine their businesses.
The Transaction will be structured as a statutory merger under corporate law in Bermuda, where both companies are incorporated, whereby ShaMaran and Gulf Keystone will merge, with Gulf Keystone as the surviving legal entity. Completion of the Transaction is subject to customary closing conditions.
The merged company resulting from the Transaction is hereinafter referred to as the “Combined Company”.
Strategic rationale
- The Transaction will create a leading independent oil producer focused on the Kurdistan Region of Iraq and Federal Iraq.
- The Transaction creates scale and diversification across four world-class fields with combined estimated working interest (“WI”) 2P reserves of 323 MMbbl1,2 and additional reserve and resource upside from ShaMaran’s recently announced investment in the Hamrin field.
- Pro-forma WI production of 53 kbopd1,3, ranking in the top 10 of Europe’s listed independents4.
- Highly complementary portfolio of four low-cost, long-life assets creating an enhanced platform for cash flow generation, shareholder distributions and growth both in the near- and medium-term, with plans to formalise the Combined Company’s distributions policy around completion of the Transaction.
- ShaMaran assets operated by strategic partner HKN Energy, a proven Kurdistan operator with a strong track-record and operational approach that aligns well with Gulf Keystone’s strategy.
- Pro-forma > USD 1 billion market cap company, with improved liquidity and access to financing.
- Intention to uplist to the Euronext Oslo Børs main market and in due course discontinue the London Stock Exchange listing to provide a single liquid listing for shareholders. Listing of the ShaMaran shares and ShaMaran’s SDRs will cease in connection with the completion of the Transaction.
- The Transaction is supported by the largest shareholder of each company. The Lundin family, through Nemesia S.à r.l. (the “Lundin Family”), holds approximately 25.6% of ShaMaran. Lansdowne Partners Austria GmbH (“Lansdowne Partners”) manages shareholdings representing approximately 13% of Gulf Keystone’s issued and outstanding shares. Each has indicated that, as at the date of this announcement, it intends to vote in favour of the Transaction. The Lundin Family will become the largest shareholder in the Combined Company and will be represented by William Lundin as the proposed Non-Executive Chair.
ShaMaran shareholders, whose shares will be cancelled in the merger, will receive as consideration newly issued Gulf Keystone shares (equivalent to an aggregate amount of approximately USD 601 million for the entire issued share capital of ShaMaran) equating to 0.07533958 shares in Gulf Keystone for each share held in ShaMaran (the “Exchange Ratio”). Subject to applicable Bermuda law, the Bye-laws of Gulf Keystone and approval by the Board of Directors of Gulf Keystone, it is intended that existing shareholders of Gulf Keystone will receive a special dividend of USD 50 million at closing of the Transaction. Following completion of the Transaction, shareholders of Gulf Keystone and shareholders of ShaMaran will each own approximately 50% of the shares in the Combined Company. For further details regarding the settlement of the merger consideration for holders of ShaMaran shares (“ShaMaran Shares”) and ShaMaran’s Swedish depository receipts (“ShaMaran SDRs”), respectively, including the conversion of ShaMaran SDRs into ShaMaran Shares, see the section “Listings and SDR program” below.
The Board of Directors of both Gulf Keystone and ShaMaran have unanimously approved the proposed Transaction and consider it to be in the best interests of each company and their respective shareholders, as further described under “Additional information pursuant to the Swedish Takeover Rules and other regulatory matters” below.
David Thomas, Non-Executive Chair of Gulf Keystone, comments:
“The merger creates a stronger company with greater scale, a highly complementary portfolio and a stronger cash flow profile. Expected near-term cash flow from ShaMaran’s assets complements the long-term growth potential of the Combined Company, enhancing our ability to invest in growth while delivering attractive and sustainable shareholder distributions. Together, we are better positioned to navigate the regional environment and to lead the next phase of value-creation as a leading independent oil producer focused on Kurdistan and Federal Iraq. The addition of Hamrin adds considerable further growth potential complementing the existing developed Kurdistan fields.”
Jon Harris, CEO and Executive Director of Gulf Keystone, adds:
“We view this combination as a natural next step for both companies. Bringing together Shaikan with the adjacent Atrush and Sarsang fields will deliver synergies and gives the enlarged company a significantly stronger platform to invest in the future development of Shaikan and Hamrin. We also look forward to working with HKN Energy as an experienced operator and partner on ShaMaran’s assets.”
Chris Bruijnzeels, Non-Executive Chair of ShaMaran, and proposed Non-Executive Director of Gulf Keystone following completion of the Transaction, comments:
“The Gulf Keystone merger is the logical continuation of the Kurdistan consolidation story, especially given the physical proximity of our assets. The ShaMaran board has been supportive of building a larger, more efficient vehicle for some time, and we expect there will be additional opportunities for growth open to the combined company, both in Kurdistan and Federal Iraq. A larger operator will deliver superior value for both Gulf Keystone and ShaMaran shareholders.”
Garrett Soden, CEO of ShaMaran and proposed Non-Executive Director of Gulf Keystone following completion of the Transaction, adds:
“ShaMaran today announced expanding into Federal Iraq with HKN Energy in the Hamrin field to create a diversified asset portfolio with an attractive production, reserves and cash flow profile. The Gulf Keystone merger amplifies that vision and is supported by the largest shareholders of both companies. We look forward to joining forces with Gulf Keystone, streamlining the combined business and building a platform for growth in Kurdistan and Federal Iraq that is backed by the Lundin Family and listed on the Oslo Stock Exchange.”
Key terms of the Transaction
Based on a Gulf Keystone share price as of close 19 October 2026 of GBp 225 (equivalent to NOK 28.18 per share using a GBP/NOK exchange rate of 12.5226 as of 19 October 2026), the Exchange Ratio of 0.07533958 newly issued Gulf Keystone shares for each share held in ShaMaran and the 2,887,504,313 currently outstanding ShaMaran Shares (settlement of long-term incentive plans of ShaMaran will be in cash), the equity value of ShaMaran in the Transaction is NOK 5.7 billion (equivalent to USD 601 million using a NOK/USD exchange rate of 9.4113 as of 19 October 2026), corresponding to a price per share of NOK 1.96.
The merger consideration to ShaMaran shareholders represents a premium of 22.9% to the ShaMaran closing share price as of close 19 October 2026, and a premium of 28.6% and 32.2% based on 30 and 90 trading days’ VWAP as of 19 October 2026, respectively (based on ShaMaran SDRs trading on Nasdaq First North Growth Market Stockholm). The share price of ShaMaran on 19 October 2026 does not reflect the investment in the Hamrin Field, which is announced today.
Adjusted for the special dividend of USD 50 million that Gulf Keystone intends to pay to its existing shareholders on closing of the Transaction, equivalent to USD 0.23 per share, the consideration to ShaMaran shareholders represents a premium of 13.5% to the ShaMaran closing share price as of close 19 October 2026, and a premium of 17.5% and 20.1% based on 30 and 90 trading days’ VWAP as of 19 October 2026, respectively (based on ShaMaran SDRs trading on Nasdaq First North Growth Market Stockholm).
Following completion of the Transaction, shareholders of Gulf Keystone and shareholders of ShaMaran will each own 50% of the shares in the Combined Company.
The number of shares issued to ShaMaran shareholders as part of the merger consideration will be based on the number of ShaMaran Shares outstanding at the time of completion of the Transaction, excluding any shares held in treasury. Under the assumption that the number of shares outstanding at completion of the Transaction is the same as at the date of this announcement, the aggregate number of newly issued ordinary shares in Gulf Keystone will be 217,543,362. On this basis, the total number of shares in the Combined Company following completion of the Transaction will be 435,086,735.
No fractional Gulf Keystone shares shall be delivered as merger consideration and the number of Gulf Keystone shares to be issued and delivered in accordance with the Transaction shall be rounded down to the nearest whole share. Any excess Gulf Keystone shares not allotted as a result of rounding shall be issued to and sold by a third party appointed by GKP, with the net proceeds distributed proportionately among the affected holders of ShaMaran Shares or ShaMaran SDRs.
Shareholder approval and support
The Transaction is subject to approval at special general meetings (“SGMs”) of Gulf Keystone and ShaMaran, with (i) in the case of Gulf Keystone, a majority of not less than three-fourths (75%) of the votes cast at the relevant SGM, and (ii) in the case of ShaMaran, not less than a two-thirds (66.67%) majority of the votes cast at the relevant SGM.
The Lundin Family, the largest shareholder of ShaMaran, holds approximately 25.6% of ShaMaran’s issued and outstanding shares, including shares represented by SDRs. Lansdowne Partners manages shareholdings representing approximately 13% of Gulf Keystone’s issued and outstanding shares. Each has informed ShaMaran and Gulf Keystone, respectively, that it supports the Transaction and that, as at the date of this announcement, it intends to vote its shares in favour of the Transaction at the relevant SGM.
The SGMs are expected to be held on or about 22 December 2026. The notices to convene the SGMs will be published through separate press releases. Gulf Keystone and ShaMaran will publish a merger information document in accordance with the Stock Market Self-Regulation Committee’s (Sw. Aktiemarknadens självregleringskommitté) takeover rules for certain trading platforms (the “Swedish Takeover Rules”) on or around 1 December 2026.
Financing
The completion of the Transaction is not conditional upon any financing, as the merger consideration in its entirety comprises newly issued ordinary shares in Gulf Keystone.
The two companies will operate independently until the Transaction has been completed. Until such date, the companies will independently finance their respective activities. It is contemplated that ShaMaran will refinance its 2029 maturity bond with approx. USD 144 million outstanding through issuance of a new bond. ShaMaran will commence marketing of its bond today. In addition, Gulf Keystone is considering new debt financing through a potential bond issue to finance some of its capital expenditures related to the further development of Shaikan and is expecting to commence marketing shortly after completion of ShaMaran marketing. These transactions are contemplated in the near term and will be announced to the market in due course, ensuring clear market and best execution for each bond.
Due diligence
When preparing for the Transaction, the companies have conducted customary due diligence reviews of certain business, financial, commercial and legal information relating to ShaMaran and Gulf Keystone, respectively. During the due diligence reviews, no material information that had not previously been made public and that could constitute inside information in relation to ShaMaran or Gulf Keystone, respectively, was provided, other than ShaMaran’s investment in a 25% stake in HKN Hamrin Ltd. and the contemplated bond issues, all of which is announced in connection with the announcement of the Transaction.
Operational and corporate update
Gulf Keystone has today provided the following operational & corporate update.
- Production and export operations continue with full well capacity of approximately 45,000 bopd
- As previously reported, a maiden top-up cargo was recently lifted following the allocation of additional barrels by Iraq’s State Oil Marketing Organisation (“SOMO”) to reconcile a portion of Q4 2025 export sales to international prices
- The Company continues to prepare for a return to drilling and field development in 2027 while progressing the installation of water handling facilities at PF-2 to unlock incremental production. Due to supply chain constraints, the Company now expects the water handling project to start-up in Q2 2027
- The Company’s balance sheet is currently debt-free, with cash of $48.2 million as at 19 October 2026
- Separately, GKP and ShaMaran Petroleum have today announced that they have agreed to merge to create a leading independent oil producer focused on the Kurdistan Region of Iraq and Federal Iraq
United Oil & Gas
United has announced positive results from the drilling rig and long-lead availability study undertaken by NRG Well Management for the Walton Morant licence, offshore Jamaica. The Study was progressed in parallel with, and in support of, the Company’s farm-out process. United’s immediate focus is firmly on concluding its ongoing farm-out discussions.
The Study identifies a clear pathway to delivering a future exploration campaign: a substantial rig pool, key long-lead requirements outlined, and a Jamaica-based logistics model identified.
Highlights:
- Supports farm-out process: provides potential farm-in partners clarity on the execution pathway for a future exploration campaign
- Substantial rig pool identified: a double-digit pool of suitable available rigs all assessed against capability, timing and regional positioning
- Campaign flexibility retained: covers the key Colibri target well (406 MMbo¹) and the deeper-water Thunderball follow-on (603 MMbo¹), a combined 1,009 MMbo² of mean prospective resource that could be targeted in a single exploration campaign
- Jamaica-based logistics model identified: combines local port infrastructure and services with specialist regional offshore services
- Long-lead requirements outlined: identifies critical equipment, sourcing options and procurement timelines
Brian Larkin, Chief Executive Officer, commented:
“The completion of this study is an important step forward for the Walton-Morant licence. It supports our ongoing farmout process, providing practical insight into rig and equipment availability and critical path items required to access the greater than 1 billion barrel mean prospective resources contained within Colibri and Thunderball, representing two targets within our portfolio of 40 leads and prospects containing over 7.2 billion barrels3 of prospective resources.
The Study has identified a substantial pool of rig candidates relevant to our potential drilling window, assessed key long lead items and outlined a Jamaica based logistics solution for potential future operations.
This gives prospective farm-in partners immediate, practical and usable information on the potential delivery of a future exploration campaign on the Walton-Morant licence.
With this work now complete, our immediate focus remains on concluding the farm-out process.”
So, another study which tells us that there is a substantial pool of both rigs and plenty of the long lead items in that ‘Jamaica based logistics solution’ which I think we knew already. There is only one ‘solution’ that UOG shareholders need right now and that is the farm-out which apparently just needs ‘concluding’…
Rig Market and Campaign Flexibility
The Study assessed the relevant offshore drilling market across established international drilling contractors and high-graded a double-digit pool of rig candidates for potential alignment with the potential drilling window. The breadth of the identified rig pool provides flexibility around future rig selection and campaign planning, and positions United and future partners to respond to rig opportunities as they become available from regional drilling programmes.
The assessment covers Colibri, in approximately 750 metres water depth, and Thunderball, a potential follow-on well in approximately 1,900 metres water depth. Colibri has mean prospective resources of 406 MMbo1, while Thunderball has mean prospective resources of 603 MMbo1 and forms part of a wider series of large, tilted fault-block structures in the Morant Basin.
Jamaica and Regional Logistics
The Study identifies a Jamaica-based logistics model combining existing port and commercial infrastructure with specialist offshore services and equipment sourced from established regional hubs. Existing Jamaican capabilities identified include port and project cargo operations, storage and laydown, heavy lifting, marine fuel supply, customs and freight forwarding. These can be complemented by specialist offshore services sourced from established regional centres.
Long-Lead Equipment
The Study has outlined the principal long-lead requirements for future drilling. Direct supplier engagement has clarified equipment availability, sourcing options and procurement timelines, enabling United and future partners to align procurement with target drilling windows.
This Study is a forward-planning and market assessment review and does not constitute a commitment, at this time, by United to drill a well. Any potential future drilling programme would be subject to, amongst other matters, the receipt of all necessary regulatory approvals from the Government of Jamaica and execution of commercial agreements.
Appendix
Colibri Prospect:
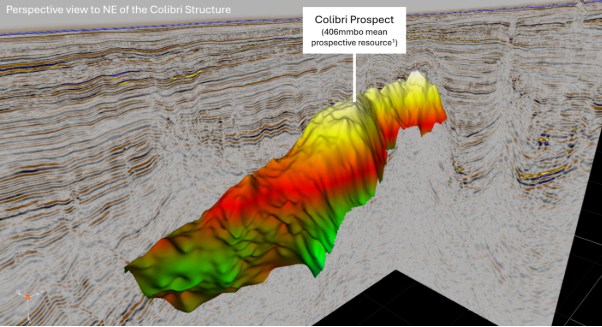
Source: UOG Interpretation of Walton Morant Seismic data
Thunderball Lead:
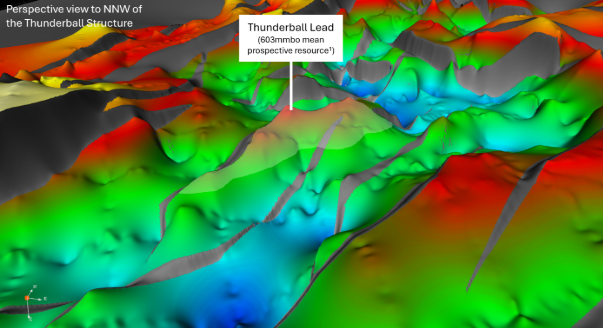
Source: UOG Interpretation of Walton Morant Seismic data
And finally…
On Monday night Spurs beat the Sky Blues to record their first win of the season.
And England got underway in the ODI Tri-series with Sri Lanka and Pakistan, in yesterdays match in Rawalpindi the hosts scored 302-9 and comfortably beat England by 87 runs and go 2/2 in the series.
Last night in the Champions League Liverpool came back well to beat villareal 4-3 whilst the Noisy Neighbours cruised past AEK Athens 5-1. Tonight the Red Devils visit Como, Villa host Viking and the Gooners visit Bayern.

Disclaimer & Declaration of Interest
The information, investment views and recommendations in this article are provided for general information purposes only. Nothing in this article should be construed as a solicitation to buy or sell any financial product relating to any companies under discussion or to engage in or refrain from doing so or engaging in any other transaction. Any opinions or comments are made to the best of the knowledge and belief of the writer but no responsibility is accepted for actions based on such opinions or comments. The writer may or may not hold investments in the companies under discussion.


